Cost of Living Comparisons: How to Estimate Your Real Monthly Budget Abroad
A realistic monthly budget beats a spreadsheet fantasy. Learn how to estimate housing, utilities, transport, groceries, and taxes with examples you can reuse.
You open a spreadsheet on your kitchen table. The rent number looks fine until you add utilities, transit, groceries, and taxes. Then it stops being "affordable" and starts being "how are we supposed to live?"
This guide helps you estimate your real monthly budget abroad using a simple method you can run for any country. You'll turn vague cost-of-living claims into a number you can actually plan around.
And yes, you'll probably adjust it once or twice. Your first draft will be wrong. That is normal. (Spreadsheets are optimistic liars.)
Start with your "baseline month," not your best-case month
Before you compare countries, you need a baseline month that matches your life. Not your fantasy version of it. Your actual routine.
Pick a month that represents your normal spending. If you have big annual bills, convert them into monthly equivalents. If you have irregular spending, average it over 6-12 months.
Here's a practical way to build your baseline month:
- List your current US monthly costs in five buckets: housing, utilities, transport, groceries, and taxes.
- Separate "fixed" items (rent, mortgage, insurance premiums) from "variable" items (groceries, dining out, subscriptions).
- Replace any US-specific costs with an "abroad placeholder" you will fill later.
Next, decide how you will treat exchange rates. Costs abroad are paid in local currency, but you think in dollars. If you plan to use USD for savings and bills, you need a rate assumption.
Use a conservative approach: take a recent average exchange rate for the last 3-6 months, then apply a small cushion. If the currency weakens, your budget should still hold.
Also decide if you want a "bare-bones" budget or a "live-like-you" budget. Many people start with bare-bones and then feel blindsided by reality. You can do both. The bare-bones number tells you the minimum. The "live-like-you" number tells you if the move is sustainable.
With SafeHavenGuide's adaptive learning system, you can store your baseline categories and update them as you collect local quotes, not guess from memory.
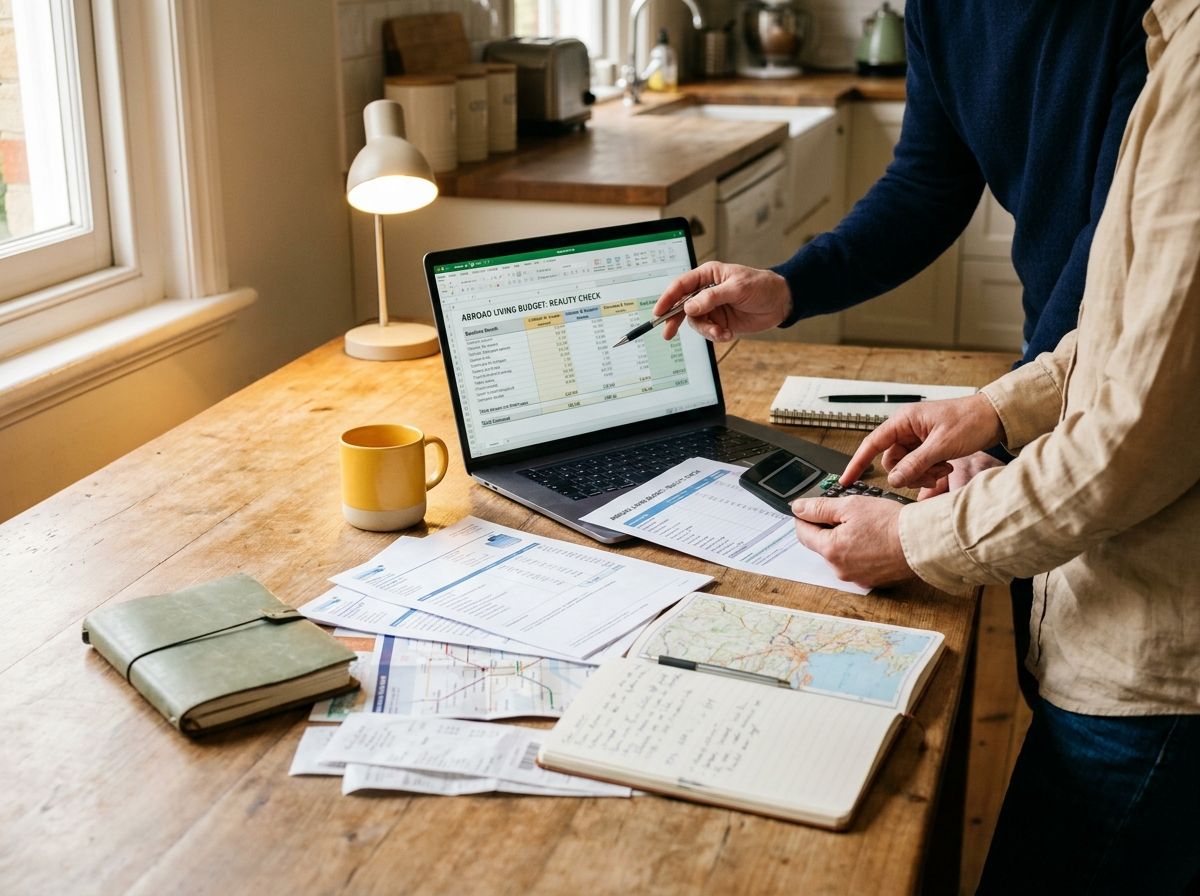
Housing: estimate rent plus the hidden add-ons
Housing is where your budget most often breaks. Not because rent is always higher, but because the "rent" you see online is rarely the full housing cost.
Start by separating rent type and contract structure. Some countries use long leases with strict terms. Others rely on shorter contracts and require deposits. Some include utilities in the rent. Others do not.
To estimate housing abroad, you need four numbers:
1) Rent (or mortgage payment)
2) Mandatory building costs (if any)
3) Utilities (sometimes included, often not)
4) One-time costs spread across the year
Those one-time costs include deposits, setup fees, and the "move-in tax" of buying basic household items.
Example scenario 1: "Maya in Lisbon"
Maya is relocating to Lisbon for a job that starts in August. She finds an apartment listing that says "rent includes water." Great. Then she asks for the utility breakdown and learns electricity and gas are separate. She also learns the building has a monthly maintenance fee for common areas.
Her real housing line becomes:
- Rent: base amount
- Electricity and gas: estimated from prior tenants or building averages
- Building maintenance: monthly fee
- Internet: separate subscription
If she only budgets the listed rent, she underestimates by a noticeable amount every month.
Example scenario 2: "Evan and Priya in Toronto" (cross-border reality check)
Evan and Priya compare cities using a rent website. The rent looks similar to what they paid in the US. Then they remember Canada handles taxes differently and sometimes has different insurance expectations for rentals. Their landlord also requires renters insurance.
This is why you should budget housing and insurance together, even if a listing doesn't mention it.
How to get better housing numbers
Use a quote-based method. When possible, contact landlords or agents and ask:
- What utilities are included?
- What is the typical monthly electricity cost in summer and winter?
- What is the building maintenance fee?
- What is the lease term and deposit amount?
If you cannot get answers, use ranges. Budget low, then stress-test at the higher end.
Utilities: use "season math," not averages
Utilities sound straightforward until you live through a hot summer or a cold winter. Many cost-of-living comparisons use one average number. Real life has peaks.
Utilities abroad usually include electricity, heating, cooling, water, and sometimes trash collection. Some homes also have service charges tied to building systems.
To estimate utilities, use season math:
- Estimate a summer month cost
- Estimate a winter month cost
- Average them into a yearly monthly equivalent
Then add a small buffer for lifestyle changes. If you work from home, you use more electricity and heating. If you have kids, you do laundry more often. If you cook at home, you may use more energy.
A helpful rule: if utilities are a percent of housing in your destination, they still behave like a percent of your comfort. You can keep them low by changing habits, but your budget should not depend on perfect behavior.
Example scenario 3: "Retirees in Valencia"
A couple moves to Valencia and plans for "mild winters." Their first winter bill is fine. Their first summer bill is not. They discover that air conditioning is the real driver, and it runs longer than they expected.
Their solution is not "panic." It is math. They estimate electricity during the hottest month, then average it across the year.
What research supports here
The idea of seasonal variation shows up consistently across energy studies and utility reporting. In most climates, heating and cooling drive large swings. In the US, utility bills also vary strongly by season, and that pattern holds in many other countries because energy demand tracks the weather.
So your job is not to find a perfect number. It is to avoid the one-number trap.
A simple utilities worksheet
Create a line item for each utility you expect:
- Electricity
- Heating fuel (if separate)
- Water
- Internet (often treated separately, but include it if you want a "living costs" view)
Then assign:
- a low estimate
- a likely estimate
- a high estimate
If you are risk-averse, use the high estimate for your "live-like-you" budget. If you are flexible and can cut discretionary spending, the likely estimate works for your baseline.
Transport: budget for ownership or for daily rides
Transport is the second biggest "surprise" category after housing. People underestimate it because they think in one mode: car or transit. Many places require you to use multiple modes.
Your transport budget depends on three decisions:
- Will you own a car?
- Will you rely on public transit?
- Will you use taxis or ride-hailing when schedules break?
Car costs include more than fuel. You may have registration fees, insurance, parking, tolls, and maintenance. Some countries also have inspections or road taxes.
Public transit costs include passes, ticket purchases, and time. Time is not money in your bank account, but it becomes money in your day. If transit is slow, you spend more on taxis to compensate.
How to estimate transport without guessing
Use a "weekly usage model."
- Count trips you will take in a typical week.
- Estimate how many you will make by transit versus taxi versus walking.
- Convert weekly costs into monthly costs.
If you plan to buy a car, add a "first-year setup" bucket. New drivers and new residents often pay extra for paperwork, insurance, and initial maintenance.
Example scenario: "A family in Berlin"
A family moves to Berlin and plans to be a "transit family." They are mostly right. But when the kids are sick or winter weather makes walking miserable, they use taxis more than they expected. (This happens to almost everyone who moves with young children.)
Their fix is budgeting for those reality days. They set a monthly taxi buffer. That prevents transport from eating into the grocery line.
A quick research note
Many cost-of-living comparisons use average transit costs without checking whether you need an annual pass. In many cities, buying a pass is cheaper, but only if you use it enough. Your weekly usage model catches that gap.
Groceries: estimate your basket, not the average headline
Groceries are personal. A "cheap groceries" country can still be expensive for your diet. A "high cost of living" country can be manageable if you shop the way locals do.
Your best method is the basket approach.
Pick 10-20 grocery items you actually buy. Examples:
- eggs
- milk or yogurt
- rice or pasta
- chicken or fish
- vegetables you eat regularly
- fruit
- bread
- cooking oil
- coffee or tea
- diapers or kid snacks (if relevant)
Then estimate how much each item costs in your destination. If you cannot price every item, price enough to represent your spending.
How to handle imported brands
Imported products often cost more. But you might not need them every week.
Decide your policy:
- Do you buy imported brands every week?
- Do you buy them for special meals only?
- Do you replace them with local equivalents?
Your budget changes a lot depending on that choice.
Example scenario: "Jordan in Seoul"
Jordan compares grocery prices and sees a "cheap produce" article. True enough. Then Jordan checks the price of the protein he eats daily and realizes it is not cheap for him. He adjusts his basket, shifts from imported items to local options, and budgets a higher amount for the protein.
He still eats well. His budget stops lying.
A practical grocery range
Create two grocery numbers:
- baseline groceries for cooking most meals at home
- higher groceries for social life and convenience purchases
Convenience purchases include pre-cut vegetables, ready meals, and delivery fees. If you plan to use those, include them.
Taxes: treat them as a separate system, not an afterthought
Taxes are not one line item abroad. They can include income tax, social insurance, payroll taxes, property taxes, and sometimes local levies.
The right tax estimate depends on your residency status, visa type, employer setup, and whether you have foreign income. So you need a tax approach that is realistic even when you do not have final paperwork yet.
Step 1: Identify your tax driver
Ask yourself:
- Will you be employed locally?
- Will you be self-employed?
- Will you keep US income and pay taxes there too?
Then identify the destination tax system you will likely fall under.
Step 2: Use a "withholding reality" estimate
If you are employed abroad, your employer often withholds taxes. That means your paycheck will show the real cost.
If you do not have a paycheck yet, estimate using tax calculators and then add a cushion. Tax calculators are helpful for ballparks, but they cannot know your exact deductions.
Step 3: Check double-tax risk (and relief)
Some countries have tax treaties with the US. Treaties can reduce double taxation, but they do not remove complexity.
Even if you plan to handle taxes yourself, you should budget time and possibly professional help for the first year. That cost is part of your real monthly budget if you spread it out.
Research references you can use without worshipping them
The US IRS publishes guidance on foreign earned income and foreign tax credits. Many expats also rely on the foreign earned income exclusion and related filing rules, but eligibility depends on residency or physical presence tests. The point is not to memorize forms. The point is to plan for the fact that taxes can follow you.
If you keep US retirement accounts or have investment income, that also changes your "real" tax math.
Put it all together: build a monthly budget with a low, likely, and stress version
Now you combine your categories into a budget that can survive real life.
Create three budget versions:
- Low budget (best-case, strict choices)
- Likely budget (what you expect most months)
- Stress budget (what happens when costs peak)
Then you choose which one matches your risk tolerance.
If you have a financial cushion and can cut discretionary spending, your likely budget might be the one you plan around. If you want stability and hate surprises, plan around stress.
Here is a simple structure you can copy:
- Housing: rent + building fees + estimated utilities-in-rent adjustments
- Utilities: electricity/heating/water averaged with seasonal math
- Transport: transit passes + taxis buffer OR car ownership costs
- Groceries: basket-based baseline + convenience allowance
- Taxes: withholding estimate + cushion for deductions and filing complexity
Then add:
- health insurance and medical costs
- childcare (if relevant)
- phone and internet
- household basics and cleaning supplies
You are not required to include every line item. But you should include the ones that repeatedly surprise people.
Example scenario: "The first month in a new country"
You land, you sign up for services, you buy a few things you did not think about, and your first grocery trip costs more because you are figuring out stores. Normal. Completely normal.
Your budget should include a "setup month" category or a monthly equivalent. Otherwise, your first month will feel like a failure even when it is just a transition.
Where SafeHavenGuide fits
With SafeHavenGuide's adaptive learning system, you can enter your baseline categories once and then update each category as you gather local quotes, not as a one-time guess.
That matters because your best budget comes from evidence, not vibes.
FAQ
How do I estimate rent if I do not know the exact neighborhood yet?
Use a range based on neighborhoods with similar commute times and housing types. Look for listings for the same apartment size category, not just "rent." Ask whether utilities and building fees are included. Then budget for the higher end until you sign a lease.
What utilities should I include in my monthly budget abroad?
Include electricity and heating or cooling. Include water if it is not bundled with rent. Internet is often separate, so decide whether you want internet inside your utilities line or in its own line item. If you can, estimate summer and winter months and average them.
How much should I budget for transport when I am new to a city?
Start with a public transit estimate based on your weekly trips. Add a taxi or ride-hailing buffer for sick days, weather, and schedule gaps. If you plan to buy a car, include insurance, parking, and maintenance, not only fuel.
Should I compare taxes using online calculators or wait for my paperwork?
Use calculators for a first estimate, then update once you have a contract or withholding information. If you are employed abroad, your paycheck will reflect the real tax impact. For the first year, budget extra time and possibly professional help if your tax situation is complex.
How can I estimate groceries for a family with different eating habits?
Use a basket approach. Choose items you buy weekly and estimate costs for those items, then adjust for convenience purchases. If you eat imported foods regularly, include them. If you are willing to swap brands, budget for local equivalents.
Your next step
Pick one destination and run the worksheet for it this week. Start with a baseline month from your current spending, then fill in housing, utilities with seasonal math, transport with a weekly model, groceries with a basket, and taxes with a withholding estimate.
When you finish, you should have three numbers: low, likely, and stress. If your stress budget is not covered by your income plus savings cushion, that is your signal to adjust the plan now, not after you sign a lease.
Join the conversation
Subscribe to comment
Join SafeHavenGuide's newsletter to leave a comment and get new posts in your inbox.